
Every conference leaves a pile of receipts: a registration confirmation, boarding passes, a hotel folio and a few restaurant slips. Before tax time, each one needs a home in your books.
Quick answer: A conference is not one expense category. Record the registration fee as professional development or training, airfare and hotel as travel, meals as meals (generally only 50% deductible in both Canada and the US), and booth costs as advertising or trade show expense. Splitting the bill this way keeps each line under the right tax rule and makes records easy to defend.
Last verified against official sources: October 2026.
This guide sets the Canadian (CRA) and US (IRS) treatment side by side, then covers virtual, local and mixed business-personal trips, freelancers, employers, three professions and bookkeeping.
Which Category Do Conference Expenses Fall Under? (With Quick Reference Table)
Conference costs spread across four or five standard categories: professional development for the fee, travel for transport and lodging, meals for food, and advertising for a booth. A three-day event can produce all of them at once, and each follows its own deduction rule.
Quick Reference Table
| Expense Type | Usual Category | Deductible Share | Where It Is Reported |
| Conference registration fee | Professional development / training | 100% when it relates to your current business | Canada: Form T2125, line 9270 (other expenses, convention rule). US: Schedule C, other expenses (line 27b on the 2025 form) |
| Airfare, train, taxi, rental car | Travel | 100% for the business part of the trip | Canada: T2125, line 9200. US: Schedule C, line 24a |
| Hotel / lodging | Travel (lodging) | 100% for business nights | Canada: line 9200. US: line 24a (lodging sits with travel) |
| Meals during the trip or event | Meals | Generally 50% | Canada: line 8523. US: Schedule C, line 24b |
| Booth, display, exhibitor package | Advertising / trade show | Generally 100% as an ordinary business expense | Your advertising or trade show account |
| Virtual conference fee | Professional development | Same as an in-person fee; no travel part | Same as registration |
| Parking, rideshare, mileage (local event) | Travel / vehicle | 100% of the business use | Travel or vehicle line, picked once and kept consistent |
Line numbers follow the CRA’s T2125 pages and the 2025 Schedule C instructions. Forms change, so check the current version before you file.
Why the Split Matters
Deduction limits and documentation rules differ by category, so a charge filed in the wrong bucket can mean a lost deduction or an overstated one. Registration is education-type spending, transport and lodging follow the travel rules in IRS Publication 463 (or the CRA travel pages), and meals carry their own cap.
Employer Reimbursements Change the Picture
If your employer reimburses you under a proper arrangement, the reimbursement is not your income and you categorize nothing on your own return. If the reimbursement is only partial, you can at most claim the unreimbursed portion, and for US W-2 employees even that is generally not deductible (see the table in the next section). State or provincial rules can differ from federal ones, so check your employer’s reimbursement policy and your local rules.
Does the Type of Conference Matter?
A clinical-skills conference for a practicing physician, a case-law update for an attorney and a platform-changes event for a developer all qualify as professional development, as long as the content maintains or improves skills required in your current work. Attending the same events to train for a new career generally does not qualify.
Canada and the US: Which Rules Apply to Your Conference Costs?
Both countries treat the registration fee as a business cost and limit meals to 50%, but they differ on convention limits and on what employees can deduct. Use the column for the country where you file.
| Topic | Canada (CRA) | United States (IRS) |
| Main form for the self-employed | Form T2125 | Schedule C (Form 1040) |
| Convention limit | Up to two conventions a year, related to your business and held by a business or professional organization in the area where it normally operates. The cap may not apply if an organization from another country sponsors the event | A convention outside the North American area is deductible only if it relates directly to your business and holding it there is as reasonable as holding it inside the area. A convention, seminar or similar meeting on a cruise ship has a separate limit of $2,000 a year with extra conditions (Publication 463, 2025) |
| Meals | 50% of the lesser of what you spent and a reasonable amount. Long-haul truck drivers on qualifying trips use 80% | Generally 50% of actual cost or of the standard meal allowance. Some transport workers under Department of Transportation hours-of-service limits use 80% |
| Fee includes meals, not itemized | Subtract $50 for each day food or entertainment is provided; that $50 a day is a meal expense at 50%. Small items such as coffee and doughnuts do not count as food for this rule | Meals billed separately are treated as meals; for a bundled fee, ask the organizer to itemize and check with your accountant |
| Employees paying their own costs | Handled under separate employment-expense rules, not on T2125 | Unreimbursed employee expenses generally cannot be deducted; Form 2106 is limited to Armed Forces reservists, qualified performing artists, fee-basis state or local government officials, and employees with impairment-related work expenses. For 2026 the IRS says taxpayers cannot claim a miscellaneous itemized deduction for unreimbursed employee travel expenses, with an exception for eligible educators |
A Worked Canadian Example
The CRA’s own example (a convention in May 2025) is a two-day convention costing $600 where the organizer does not itemize meals. Subtract $50 for each of the two days, which leaves $500 as the convention expense and $100 as a meal and entertainment amount. The $100 is limited to 50%, so $50 is deductible, and the total deduction is $550.
When to Ask an Accountant First
Cross-border cases are the usual trouble spot: a Canadian resident attending a US event, a US citizen working in Canada, or an event sponsored from abroad. These can change which rules apply, so confirm with a professional before relying on either column.
How to Categorize Each Conference Expense Component Separately
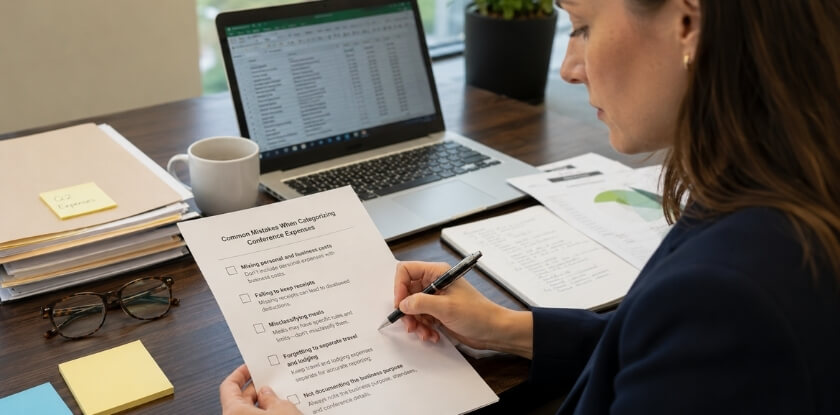
Split the bill into four parts: the registration fee, travel and lodging, meals, and exhibiting costs if you had a booth. Each part has its own deduction rate and its own place on the return.
Registration Fee
The registration fee is what you pay to attend the event itself. For business owners, freelancers and the self-employed it goes under professional development or education and training in the chart of accounts. If the conference relates directly to your current trade or business, the full fee is an ordinary and necessary business expense. IRS Publication 970 covers education costs more broadly, but for a working professional the cleaner test is whether the event maintains or improves skills required in your existing work. A graphic designer at a design conference passes that test easily. Someone attending a conference in a field they have not entered yet generally does not.
Employees paying their own fee should read the employee row in the table above before assuming a deduction exists. Employer reimbursement is usually the practical route.
Document the business purpose. Write the name of the conference and how it relates to your work, and keep the note with the receipt.
Travel and Lodging
Travel and lodging are categorized separately from the registration fee and carry their own rules. Airfare, train tickets, rental cars and taxis to and from the venue are travel expenses, and so is the hotel, including nights you must add because of flight logistics. On the US Schedule C, lodging and transportation for overnight business travel both go on line 24a. The CRA likewise lists public transportation fares and hotel accommodation as travel costs. Both are deductible for the business part of the trip, unlike meals. Keep receipts and note the business purpose.
The trip has to be primarily for business. If you add four beach days to a three-day tech conference, you must allocate costs carefully, because personal days can cost you part of the transportation deduction if the trip tips into personal territory. The mixed-trip section below explains the test.
For a local event where you drive your own car, track mileage. The IRS publishes the business standard mileage rate every year: 70 cents per mile for 2025, and for 2026 it is 72.5 cents from January to June and 76 cents from 1 July. Actual vehicle costs are the alternative, if you already use that method for the vehicle.
If your employer covers travel under an accountable plan, those reimbursements are not your income and you do not deduct them; the employer does.
Meals
Meals are limited to 50% in both countries, whether you eat alone between sessions, attend a sponsored dinner or take a client out during the event. This holds at a medical, tech or legal conference alike. Because meals are the one part with a cap, put them in their own account. That makes the 50% limit easy to apply at year end and stops the wrong rate being used on the whole trip. Keep receipts that show the business purpose, who attended and where.
If you use the US standard meal allowance (federal per diem rates for meals and incidentals) instead of receipts, the 50% limit still applies. The allowance simplifies recordkeeping, but you still document the trip’s business purpose. For travel from 1 October 2026 to 30 September 2027, the standard GSA rate is $113 for lodging and $68 for meals and incidentals, and many cities have higher rates (GSA bulletin FTR 27-01).
If the registration fee includes meals, treatment differs by country (see the table above). In Canada, take $50 a day out of the fee as a meal. In the US, a separately billed meal amount is a meal cost, and a bundled fee is usually left as one professional development expense; ask your accountant about large amounts.
Trade Show and Exhibiting Costs
Exhibiting is promotion, not education. Booth rental, display materials, signage and branded giveaways go under advertising and marketing or trade show expenses, depending on your chart of accounts. Shipping for displays goes under shipping and freight or inside trade show costs.
Staff travel and lodging to run the booth is ordinary travel. Product samples given away may belong in cost of goods or promotional materials, depending on how you track inventory. Exhibiting costs are generally deductible as ordinary and necessary business expenses without a special cap like the meals rule. Freelancers and sole proprietors report them on Schedule C (US) or T2125 (Canada), and an incorporated business deducts them on its entity return.
The practical reason to keep exhibiting separate from attendance is clean reporting. A company that attends a conference and also runs a booth is doing two distinct things, and the books and tax records should show that clearly. Organizing your own event is a different job again, with venue, catering and AV lines that make up the cost of running a conference.
Expense Categorization for Online and Virtual Conferences
A virtual conference has one main cost, the registration fee, and it is categorized exactly like an in-person fee: professional development when it keeps your current skills sharp. There is no travel, lodging or per diem to record.
Registration Fees for Virtual Conferences
Deduct it the same way as an in-person fee: under professional development or continuing education when it maintains or improves skills in your current trade, or as a general business expense when it is mainly for networking or industry knowledge. Self-employed filers report it with other conference fees (T2125 line 9270 in Canada, the other expenses section of Schedule C in the US). Describe it clearly, for example “online conference registration, [conference name]”.
Employees who pay out of pocket are in the same position as for any other conference: see the employee row in the table above. IRS Publications 463 and 970 are worth reading if you are unsure whether a specific virtual event qualifies. For licensed professionals, a virtual event taken for required continuing education usually fits professional development better than a generic business expense, which also keeps records clean if you are asked to show the cost was ordinary and necessary.
Travel, Meals and Equipment
This is where virtual events genuinely differ. Attending from your home office or regular workplace means no flight, no hotel and no per diem rate to calculate. The entire cost is typically the registration fee, plus any software or equipment you buy specifically to take part, which may be a separate business expense.
Lunch eaten at your desk during a stream is generally a personal meal, because there is no business associate and no travel. If a sponsor delivers a meal as part of the program, ask your accountant and keep documentation of the business context. If your employer sends you to a co-working space just for the event, reasonable transport there may be reimbursable; this is an edge case to check.
Virtual Trade Shows and Hybrid Events
Exhibiting online replaces booth construction and shipping with platform fees, digital asset design, sponsored placement inside the event software and staff time for live demos. These sit under trade show or advertising costs, depending on how your chart of accounts is set up in QuickBooks or whichever system you use. If part of your fee is a virtual exhibitor package, record it separately from attendee-only access.
If you join a hybrid event remotely, treat it as a virtual conference: the fee is deductible, there is no travel, and meals are personal.
Categorization for Local Conferences (Without Travel)
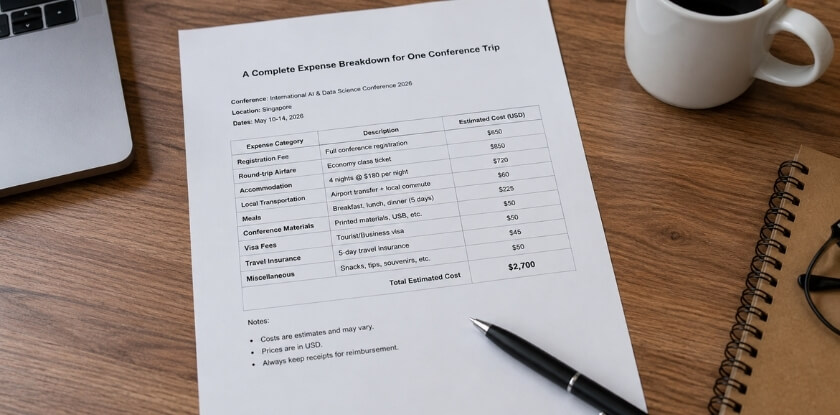
A local conference you drive to has no lodging cost, so you are left with the registration fee, meals and parking or transit. The fee goes to professional development, meals follow the 50% rule, and parking goes to travel or vehicle costs.
Registration Fees
The fee for a local conference is a business expense, the same as any other. Self-employed people in the US deduct it on Schedule C under other expenses, or under an education and professional development account in their books, depending on the chart of accounts. In QuickBooks you can code it as “Professional Development” or “Training”; both work as long as you stay consistent.
If your employer pays or reimburses under an accountable plan, it does not appear on your personal return at all. If you pay out of pocket as a US W-2 employee and your employer will not reimburse you, check with a tax professional before assuming you can deduct it. A tech or legal conference focused on your industry is a professional development or continuing education expense, while a trade show where you exhibit has its own treatment (see the exhibiting costs above).
Meals at a Local Conference
The 50% limit applies exactly as it does for an out-of-town conference. Lunch bundled into the fee follows the rules in the table above: in Canada, $50 a day comes out of the fee as a meal at 50%. If the program provides meals and the cost sits inside a US registration fee, you do not need to split it out unless the registration confirmation itemizes it; deduct the whole fee as professional development and move on. A separate dinner with clients or colleagues after the sessions is a meal at 50%. Keep the receipt and note who you met and why.
Parking and Local Transportation
A local conference has no lodging cost, but parking, transit and rideshare are still deductible business costs, whether the event is fully in person or a hybrid where others join remotely. Put them under “Travel” or “Auto and Transportation” in QuickBooks; either works, but pick one and use the same account all year. If you drive your own vehicle and claim mileage, that is a vehicle expense rather than a travel item. Mileage or parking may qualify as travel under IRS Publication 463 when you are traveling away from your regular place of business.
What You Cannot Deduct
An event that is only loosely related to your business, or mostly social, does not qualify. A freelance designer at a marketing conference for their industry is fine. The same designer at a wellness retreat labelled “professional development” is a hard case to support. Personal meals near the venue, unrelated to the program or a business conversation, stay personal.
Keeping Records for Local Events
Because local events feel informal, people skip the paperwork. That is a mistake: a small expense does not lower the documentation requirement. Save the registration confirmation, parking and meal receipts, and a note of the business purpose. Create the accounting entry when you pay, attach the receipt to it and add a memo with the conference name. A sample note:
[Conference name], [city], [date]. Attended sessions on [topic] to keep my [skill] up to date for client work with [type of client]. Parking receipt and lunch receipt attached.
Part-Personal, Part-Business Conference: How to Split the Costs
Only the business part of a mixed trip is deductible, and the first test is the trip’s primary purpose. If the trip is primarily for business, you can deduct business-related costs, including getting to and from the business destination. If it is primarily personal, travel costs are not deductible. Plenty of conferences land in between: a four-day event with two days of relevant sessions and two days of sightseeing with your spouse, or a weekend added before the sessions to explore the city.
The Primary Purpose Test
For travel within the US, the IRS (Publication 463) says a primarily business trip with a personal side trip lets you deduct only the business-related costs. Days spent on business versus personal activity are an important factor in showing the purpose. A business day is any day you attend sessions or work with clients, and travel days generally count. A day of pure sightseeing does not.
For travel outside the US, Publication 463 treats a trip as entirely business in four situations, for example when you are abroad for a week or less, or spend less than 25% of the time on personal activities. Otherwise you allocate travel costs by counting business days against total travel days. In Canada, the CRA allows travel costs incurred to earn business income, so the same logic of deducting only the business part applies.
How to Allocate Costs Once the Trip Qualifies
Airfare and direct transportation. When the trip is primarily business and the destination is the conference city, getting there and back is deductible. A side trip elsewhere is allocated separately. The IRS gives an example where a business trip extended by a stop at the traveler’s parents’ home allowed $1,633.50 of a $2,165 total.
Lodging. Lodging is prorated by night. If you stayed six nights and four were business nights, deduct four-sixths of the hotel cost. Keep the conference schedule to show which nights were business.
Meals. Only meals on business days qualify for the 50% limit. Meals on personal days are not deductible.
Registration fees. The fee is deductible in full when the conference itself serves a business purpose. You do not prorate it for personal time added around the event.
Bringing a Spouse or Family Member
A spouse’s or companion’s travel is generally not deductible. If your spouse joins you but is not an employee and has no genuine business role at the event, none of their expenses count: not airfare, not their share of a room upgrade, not their meals. The exception is a person who is your employee, has a bona fide business purpose for being there, and would otherwise be allowed the deduction. Typing notes or similar incidental help does not establish a business purpose.
For the hotel room, deduct only the single-occupancy rate. In the IRS’s example, a double room cost $199 a day and a single $149, so only $149 was deductible. Keep a record of what the single rate would have been. Employees reimbursed under an accountable plan should follow the employer’s policy closely. Most plans will not reimburse personal portions or spousal travel.
Documentation You Will Need
Mixed-purpose deductions depend on records. Keep a written log with the date, the business activity and the cost tied to each day. A printed agenda, session attendance records or calendar entries showing meeting times all help show which days were genuinely business. Self-employed filers and employees face the same documentation standard. Split the trip into separate entries when you record it: business nights as lodging, personal nights coded non-deductible. Splitting later from one hotel receipt is slower and error-prone.
IRS Publication 463 covers the domestic trip rules in detail, and Publication 970 applies when the event is better treated as an education expense than as business travel.
Conference Expense vs. Training and Education Expense: What Is the Difference?
A conference or seminar that maintains or improves skills for your current work is a business expense. Formal education that qualifies you for a new trade or profession is not, and IRS education tax benefits such as the Lifetime Learning Credit cover tuition-type programs, not industry conferences.
How the Line Is Drawn
The question is whether the main purpose is to keep up in your current job or to prepare you for a different one. An annual medical conference to stay current on clinical practice is professional development tied to your existing career. A course that would qualify you for a different field does not qualify as a business expense, however you label it.
Publication 970 covers education tax benefits such as the Lifetime Learning Credit and tuition deductions, which apply to formal education programs. A registration fee for a trade show or professional conference is a business expense on Schedule C (self-employed), with unreimbursed employee costs limited as described in the table earlier. In Canada it falls under the convention rule on T2125. It is not an education credit.
When a Conference Qualifies as Professional Development
Events aimed at your current profession fit cleanly: a tech conference on tools you already use, a legal conference for continuing legal education (CLE) credits, or a medical conference for certification renewal. A freelance developer at a software architecture conference qualifies. The same developer paying for culinary school does not, even though it is “something new.”
You can log these under “Professional Development” or “Continuing Education.” Either works if it is consistent and separate from personal education.
When Expenses Cross Into Education Territory
Some multi-day workshops mix networking with formal coursework. Allocate the cost by the time given to each purpose, the same way you split a part-business trip. A portion that counts as continuing education for a licensed profession fits professional development. A portion that looks like enrollment in a degree or certification program needs a separate check against IRS Publication 970, which may point to education tax credits instead.
The Practical Test
For most people at industry events, the expenses are business expenses, not education credits: the registration fee, travel and lodging flow through Schedule C or the employer’s accountable plan, meals follow the 50% rule, and per diem rates may apply to travel. If you are unsure whether something is a conference or a formal education expense, ask whether the event helps you do your current job better or prepares you for a different one. Your honest answer usually settles the categorization.
Claiming Conference Expenses for Self-Employed Individuals and Freelancers
Self-employed people claim conference costs on their own return: Schedule C in the US, Form T2125 in Canada. Nobody reimburses you, so the deduction depends on how well you categorize and document each cost.
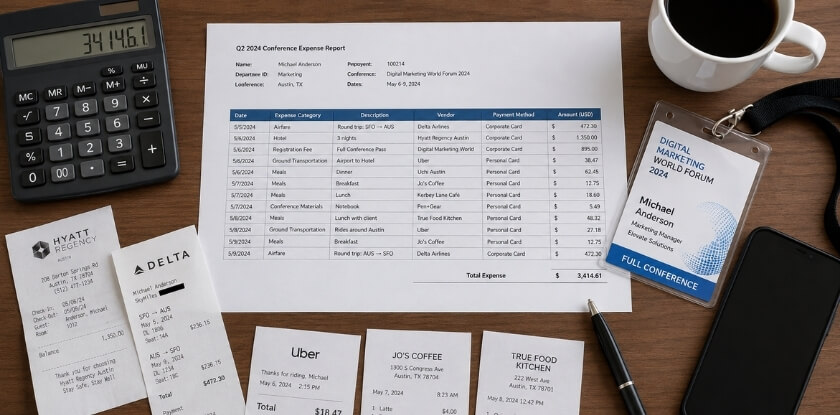
Where Self-Employed Filers Claim These Deductions
On the US Schedule C (2025 instructions):
- Registration fees go under other expenses with a description such as “conference registration, [conference name]”. If you are also exhibiting, the booth part belongs under advertising instead.
- Travel and lodging share one line, 24a.
- Meals go on line 24b, at the deductible percentage, which is 50% in most cases.
On the Canadian Form T2125, convention expenses go on line 9270, travel on line 9200 and meals on line 8523. If you are unsure where a cost fits, IRS Publication 463 and the CRA convention pages are the reference documents.
Tracking and Software
Proper categorization matters all year, not just at tax time. If you use QuickBooks Self-Employed or QuickBooks Online, set up expense accounts that map to those lines and tag registration separately from travel and meals, so year-end reports show the real breakdown. A lump-sum “conference costs” account creates extra work at filing. Keep receipts for every component and record the amount, date, place and business purpose of each. A single registration receipt is easy; travel and meals across a multi-day event take more discipline, but the standard is the same. The professional development framing does not change the deduction, but it helps you explain the business purpose if you are asked.
If a conference is tied to continuing education, such as a medical event with CME credits, a legal event for CLE or a tech event on skills you use with clients, the fee may be treated as an education-type expense rather than an ordinary one. For a self-employed person the practical test is the same: does it maintain or improve skills in your current line of work? If so, it is deductible. Training for a fundamentally different business generally is not.
Virtual and Local Conferences
For a virtual or online event, the fee is typically the only deductible cost, since there is no travel or lodging. For a local event where you drive from your home office, add the fee, parking or transit, and meals at the 50% limit; standard mileage or actual vehicle expenses may apply if you drive your own car.
Employees Who Also Freelance
If you have a day job and freelance on the side, conference costs for the freelance work go on Schedule C (or T2125) for that activity. Form 2106 is not the place for them. If an employer reimburses a conference tied to your day job under an accountable plan, there is nothing to claim, so do not also claim the same expense on your freelance return.
Record the Purpose at the Time
A large, visible deduction, such as a conference in a resort city, draws questions if the paperwork is thin. Write the business purpose when you pay, not months later. Note who you met, which sessions you attended and how they relate to your work. A record made at the time is worth more than an explanation after the fact.
Employer Perspective: Conference Expense Reimbursement Policy
Employers should reimburse conference costs under an accountable plan, because reimbursements under one are not taxable wages. This section describes US rules; Canadian employers should check CRA guidance on reimbursing employee expenses.
Setting Up an Accountable Plan
Under IRS Publication 463, an accountable plan requires a business reason for the expense, adequate accounting by the employee, and return of any excess. The IRS safe-harbor periods are accounting for expenses within 60 days after they were paid or incurred, and returning any excess within 120 days. Amounts paid this way are not part of the employee’s taxable wages. A non-accountable plan has no such requirements. Reimbursements under it are treated as wages and reported on the employee’s W-2.
Employees who are not reimbursed at all generally cannot deduct the cost on a federal return, which is a good reason to have a written policy. Getting this wrong creates problems at audit time, or leaves employees taxed on reimbursements that should have been tax-free.
How to Categorize Conference Costs in Your Books
Lumping everything under “conference expenses” is fine for internal reporting, but many companies split it for cleaner financials and easier tax preparation. Use a parent account such as “Conference and Events” with sub-accounts for registration, travel, lodging and meals. Registration is a business expense, often under professional development; travel and lodging are deductible for the business nights of a primarily business trip; meals stay separate so the 50% limit is easy to apply. Exhibiting costs go under marketing or advertising instead, because the purpose is customer-facing promotion rather than employee education. A step that is easy to miss when everything is pooled is applying the meals limit at tax time.
Coding by Role
For a medical or legal conference tied to continuing education, you may code the fee under continuing education if your policy tracks CE spending for compliance or HR reasons. A tech conference goes under professional development or business travel, depending on whether the employee attends as a learner, a speaker or a company representative.
Writing and Enforcing a Clear Reimbursement Policy
A written policy protects the company and gives employees a clear process. At minimum it should cover eligible expenses, any per diem rates for meals and incidentals, receipt requirements, the submission deadline, and whether personal expenses during a business trip are ever partly reimbursable. Using federal per diem rates (published by GSA, and described in IRS Publication 463) simplifies meal and lodging reimbursement because employees do not submit every coffee and dinner receipt, and it makes accountable plan compliance easier to manage.
For mixed trips, state that lodging and meals on personal days are not reimbursable and are not business expenses on the company’s books. Explaining this before booking avoids disputes and claims that have to be rejected or corrected afterward.
Industry-Specific Examples (Medical, Tech, Legal)
The categories do not change by profession: registration is professional development, travel and lodging are travel, meals are limited to 50%, and booth costs are advertising. What changes is how clearly the event meets the “ordinary and necessary” test. These are illustrative examples, not rulings.
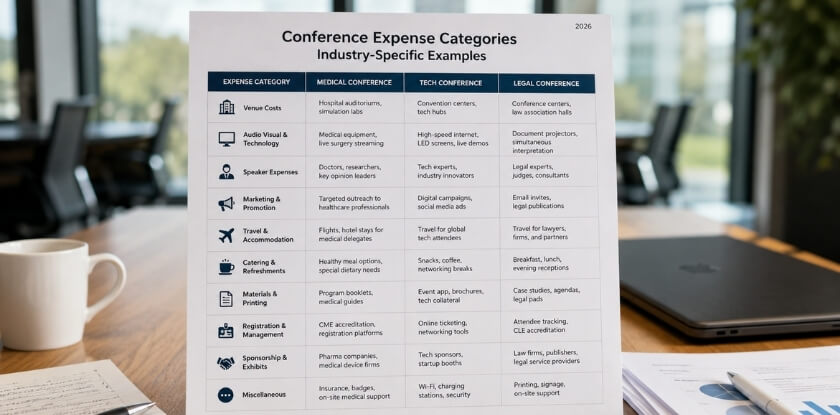
Medical Conferences
Physicians, nurses and other healthcare professionals attend for continuing medical education (CME) and to stay current clinically. Both are legitimate business purposes, but how you categorize the cost depends on your employment status.
A self-employed physician or practice owner puts CME conference costs on Schedule C: registration under other expenses with a clear description, travel and lodging on their lines, and 50% of meals. An employed physician who is not fully reimbursed is in a weaker position under current US rules, so pushing for employer reimbursement through an accountable plan is worth more than trying to claim the cost personally.
A significant educational component that maintains or improves skills in your current work strengthens the professional development classification (see IRS Publication 970). A conference that mainly qualifies you for a new specialty or career path does not pass the test. A resort destination needs extra care: if a cardiologist attends a cardiology symposium in a beach city, the CME sessions are legitimate and the extra beach days are personal.
Tech Conferences
Tech professionals (developers, engineers, product managers, consultants) attend everything from large expos to small developer summits and vendor training events, so the category depends on purpose. A consultant attending to stay current with frameworks records the fee as professional development on Schedule C. If the same person is exhibiting a product or running a booth, those costs (rental, display materials, shipping hardware to the venue) are trade show or marketing expenses, not education. In QuickBooks, track them under a “trade show” or “marketing” account. Mixing exhibiting with attendance creates confusion at tax time and misdescribes each cost.
A virtual tech conference is categorized like an in-person one, with no separate IRS rule for virtual attendance. For example, a $500 online fee is a professional development expense under the same rules. When an employer reimburses registration and travel but caps the amount, the amount above the cap is generally a personal cost for a US employee, since the Form 2106 deduction is not available to most employees.
Legal Conferences
Most state bars require a set number of CLE credits per reporting period, and conferences are a common way to earn them. A self-employed attorney, or a partner treated as self-employed for tax purposes, follows Schedule C rules: registration, travel, lodging and 50% of meals during a CLE conference are deductible business expenses. IRS Publication 463 governs the travel part, including the per diem option for meals if you prefer it to tracking actual costs. A local bar association event with no travel is just the fee, coded in QuickBooks as professional development or dues and subscriptions, depending on whether membership is bundled.
For a multi-day event in another city, allocate precisely. If an attorney extends a three-day conference in Chicago to five days, the three conference days are deductible and the two personal days are not, including those hotel nights and meals.
A conference in an area of law you do not practice can be challenged as training for a new trade. A criminal defense attorney attending a real estate conference to change practice areas is in a gray area; a real estate attorney sharpening existing skills is not. Document your intent and ask a tax professional if it is unclear.
How to Categorize Conference Expenses in QuickBooks
QuickBooks has no built-in “conference” category, so you split costs across existing accounts. That is the right approach anyway, because it mirrors how the tax rules treat each part. Other accounting software works the same way.
Setting Up Your Chart of Accounts
Check that you have these accounts before entering anything:
- Travel: flights, trains, rental cars, taxis and lodging
- Meals: all food and drink (50% limited)
- Professional Development or Education: registration fees and course materials
- Marketing or Advertising: booth fees and promotional materials
- Office Supplies or Other Business Expenses: printed handouts and similar items
If you file on Schedule C or T2125, these account names should map to the corresponding lines on your return, so have your accountant confirm the mapping once, especially if travel and professional development share a trip. A dedicated “Conferences and Seminars” sub-account under Professional Development keeps conference fees visible and separate from general training or subscriptions. Some bookkeepers instead keep a whole overnight trip under a Travel parent with sub-accounts for registration, airfare, lodging, meals and ground transport. That is a bookkeeping choice; the tax treatment of each part stays the same.
Entering the Registration Fee
The fee goes under Professional Development, Education or Other Business Expenses, depending on how your books are structured and the nature of the conference. Enter the conference organizer as the vendor, pick the category, and add a memo with the conference name and date. The memo matters if you are ever asked what the expense was for. If you paid by card, categorize the transaction that already appears in your bank feed rather than entering it twice.
Splitting a Lump-Sum Charge
When a single fee bundles registration, meals and materials, split the transaction across accounts. As an example only, a $900 charge that includes $700 of registration and $200 of meals becomes $700 to Professional Development and $200 to Meals. Take the split from the organizer’s invoice. If the invoice does not itemize meals, the CRA’s $50 per day rule applies in Canada; in the US, ask your accountant. Getting the split right matters: lumping everything into one category can overstate your meals deduction or understate your education deduction.
Entering Travel, Lodging and Meals
Flights, hotel and ground transport go to Travel. Enter them as separate lines if they were separate charges. If you record a per diem, note in the memo that it is a per diem and not an actual-cost reimbursement. Meals entered separately, such as airport food, a restaurant dinner with clients or coffee during a conference break, go to the Meals account. Do not combine a client dinner with a travel meal in one entry unless they were the same event; separate entries are easier to substantiate. If you were exhibiting, booth fees and printed promotional materials belong under Marketing or Advertising, not Professional Development.
Tagging Expenses for Reporting
If you attend several events a year, tag each expense with the event name, for example:
[Event name] 2026, [category]
Filtering by that tag gives the full cost of any one conference in seconds. It is especially useful when professional development costs must be reported separately or reimbursed by an employer under a specific policy. For virtual conferences, create a dedicated sub-category rather than a catch-all, because the choices you make now decide how useful your reports are at tax time and how quickly your accountant can verify the deductions.
Attaching Receipts
Attach the receipt image at the time of entry. IRS Publication 463 requires substantiation for travel and business expenses, and for an online conference you can save the confirmation email as a PDF and attach that.
From our experience at MS International: Our conferences are held in person at venues in the Greater Toronto Area. Listener registration is for attending without presenting, and the event pages currently list Author Early Bird US$499, Author Regular US$599 and Listener US$499. Fees are non-refundable and non-transferable, apart from rare written exceptions, so keep your payment receipt for your records. Our invitation letter is issued within 3 to 5 business days after payment clears and supports, but does not guarantee, a visa application. We do not give tax advice, so ask your own accountant how to book the fee.
FAQ: Conference Expense Categories
Classifying a conference on your books or tax return involves the registration fee, travel claimed separately, meal deductions and employer reimbursement, with Canadian rules in view.
Is a conference registration fee tax-deductible?
Yes, when the conference relates to your current business or profession. Self-employed people deduct it on Schedule C (US) or Form T2125 (Canada). Employees generally cannot deduct unreimbursed fees on a US federal return, so employer reimbursement matters.
What expense category does a conference registration fee fall under?
Professional development or education and training. In QuickBooks, code it to a professional development or other business expense account, whichever fits your chart of accounts.
Are conference travel costs deductible separately from the registration fee?
Yes. Airfare, hotel and ground transport are travel expenses, tracked separately from the fee. Lodging and transport are deductible for the business part of the trip, while meals are limited to 50%.
Can I deduct the full cost of meals at a conference?
No. Business meals, including meals during a conference, are generally limited to 50% in both Canada and the US. Long-haul truck drivers in Canada and certain transport workers in the US have an 80% limit.
How many conferences can I deduct in Canada?
Up to two a year. The CRA allows a deduction for up to two conventions a year that relate to your business and are held by a business or professional organization in the area where it normally operates.
Where do I deduct conference expenses if I am self-employed?
On Schedule C in the US (travel and lodging on line 24a, meals on line 24b) or Form T2125 in Canada (conventions on line 9270, travel on line 9200, meals on line 8523).
Are virtual conference fees categorized the same way as in-person ones?
Yes. A virtual registration fee is a professional development expense. With no travel involved, the fee is usually the only deductible cost, plus any software or equipment needed to take part.
What if my employer reimburses my conference costs?
You do not include an accountable-plan reimbursement in income and you claim no deduction. If the plan is not accountable, the reimbursement is treated as taxable wages. Unreimbursed US employees face major limits on deducting these costs.
How do I handle a conference that mixes business and personal time?
Deduct only the business portion. Extra hotel nights and personal meals are not deductible. Airfare to the conference city can still be deductible if the primary purpose of the trip was business, but document that clearly.
Do trade show and exhibiting costs fall under the same category as attending?
No. Booth rental, display materials and promotional items usually go under marketing or advertising. Attending as a participant is a professional development or travel cost. Keeping them separate gives cleaner reports.
Does the per diem rate apply to conference travel?
Yes, in the US. You can use federal per diem rates for meals and incidentals instead of receipts; the standard rate from 1 October 2026 is $68 a day for meals and incidentals. The 50% limit still applies to meals, and you still record the business purpose.
Is a medical, legal or tech conference treated differently for tax purposes?
The categories stay the same. The type of conference only affects whether the cost counts as continuing education or professional development for a licensed profession, and how clearly you can document the business need.
Conclusion
Split every conference bill into registration, travel, meals and exhibiting, and give each its own category. Apply the 50% limit to meals, keep each receipt with a note of the business purpose, and use the column for the country where you file. When a case is unclear, such as a mixed trip, a cross-border event or an employee deduction, ask an accountant who knows your industry.
Disclaimer: This article is general information, not tax, accounting or legal advice. Tax rules differ by country, change over time and depend on your situation. Confirm with a qualified accountant, the CRA or the IRS before you file.